Dashboard / 15-minute range retest
s37-A Her breakeven, no CPI days★ Main
NAS100 · 1m chart · a variation of 15-minute range retest · paper account since 2026-11-03
Retest of the 15-minute range with the range candle's colour, stop to entry on the first 5-minute break of structure, no target.
Backtest 2019-today: 1,117 trades, 9% wins, +329.4R, largest drop 39.1R. 2019-23 +183.5R, 2024-26 +145.9R, 2026 so far +48.5R.
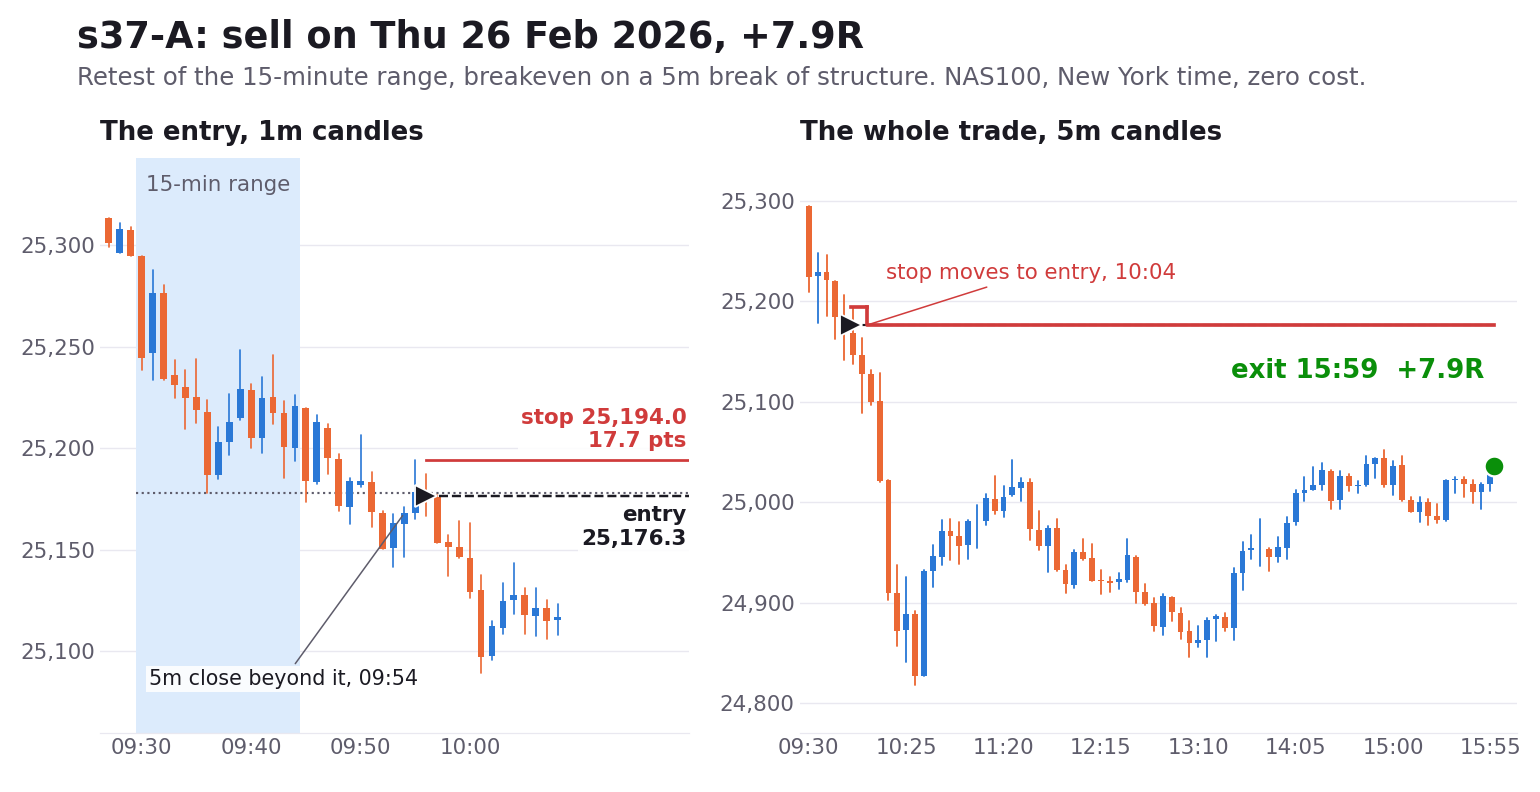
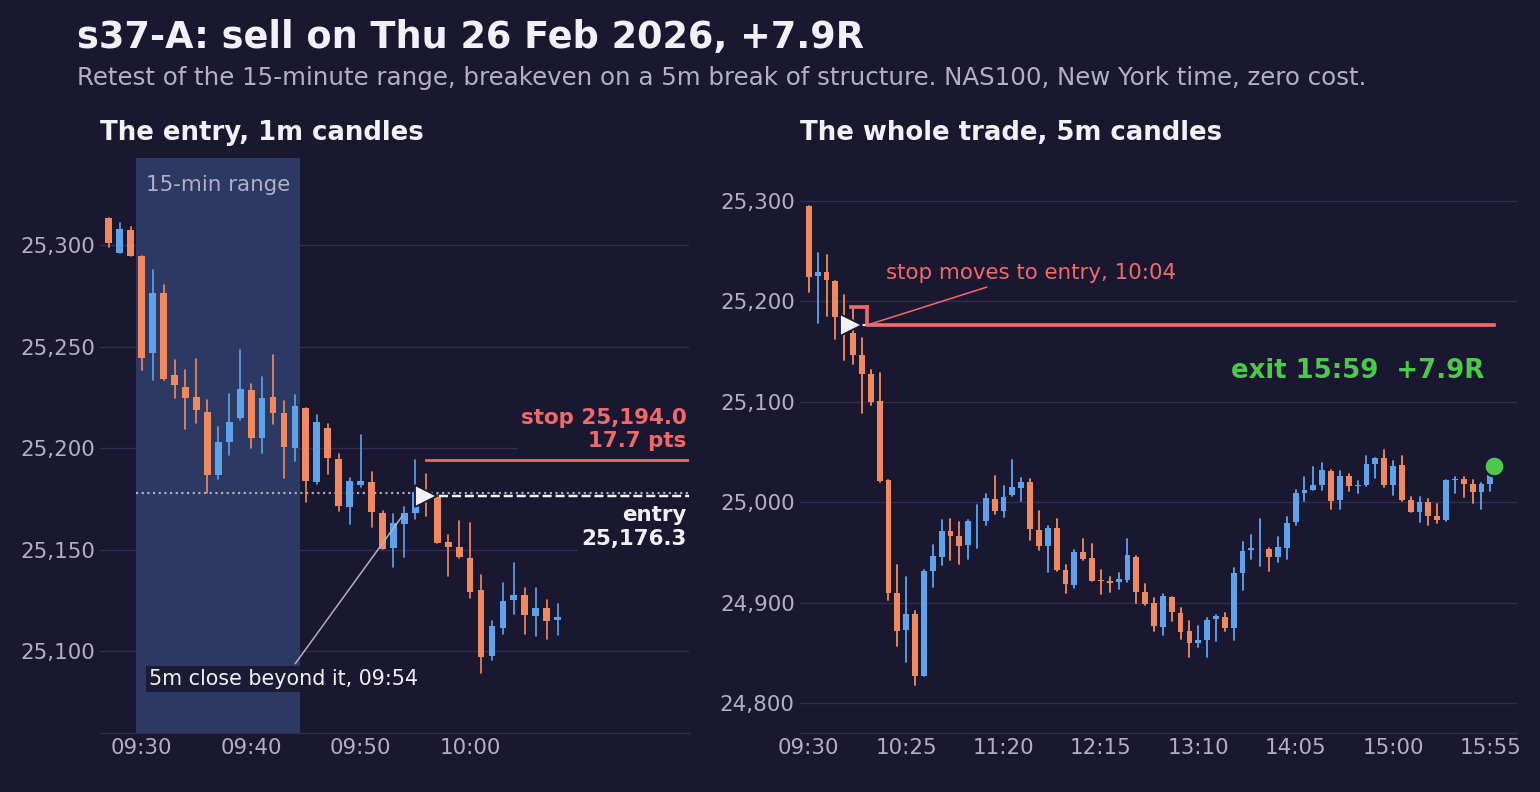
The rules it shares with every variation are on the strategy page.
All 21 settings of s37-A
Range start = 09:30Range length = 15Candle bias = yesTouch tolerance = 0.05Last entry = 12:00Smallest stop = 0.0003Largest stop = 0.004Breakeven = structureTarget = offSkipped news = ["CPI"]Exit time = 16:00tp r = 2use be = nobe trigger r = 1.5sl atr mult = 0stop steps = []trail start r = offtrail dist r = 1use tp = nopartial r = offpartial frac = 0.5Balance (R)
Calendar
Closed trades
| Year | Trades | Win % | Result |
|---|---|---|---|
| 2019 | 144 | 12% | +22.6R |
| 2020 | 139 | 9% | +84.5R |
| 2021 | 131 | 11% | +32.0R |
| 2022 | 149 | 9% | +39.2R |
| 2023 | 152 | 4% | +5.3R |
| 2024 | 149 | 11% | +62.3R |
| 2025 | 138 | 9% | +35.2R |
| 2026 | 115 | 12% | +48.3R |
Dukascopy data until 2026-10-05, in R at zero cost (R = the amount risked on a trade). Your own spread, commission, account and risk go in the Money calculator tab. Settings were partly chosen by looking at this history, so the live account is the real test.
Turn the backtest's R into money for your own account: starting balance, risk per trade (fixed or compounding) and your broker's costs. Nothing else on the site uses money.
Balance after each trade
| Year | Trades | R before costs | R after costs | Profit | Return |
|---|---|---|---|---|---|
| 2019 | 144 | +22.6R | −7.3R | −$730 | −7.3% |
| 2020 | 139 | +84.5R | +68.4R | +$6,842 | +73.8% |
| 2021 | 131 | +32.0R | +19.5R | +$1,954 | +12.1% |
| 2022 | 149 | +39.2R | +28.6R | +$2,857 | +15.8% |
| 2023 | 152 | +5.3R | −9.0R | −$903 | −4.3% |
| 2024 | 149 | +62.3R | +51.6R | +$5,157 | +25.8% |
| 2025 | 138 | +35.2R | +26.8R | +$2,681 | +10.6% |
| 2026 | 115 | +48.3R | +43.6R | +$4,358 | +15.6% |
Replays the backtest trades with raw costs: 1.00 spread. A trade's cost in R = cost ÷ its stop distance, so tight stops pay more R. Risk is set when a trade opens; trades can overlap, like the backtest. Year = the year the trade opened (UTC); return = profit ÷ the balance at the year's first trade. Not included: swap / overnight financing, taxes. Past results, not a forecast.
This variation's backtest trades on a prop firm account: pick a firm, an account size, a period and your risk per trade. Costs come from the Money calculator tab (now: raw costs: 1.00 spread).
FTMO · 2-Step Challenge: Target 10% then 5% · max loss 10% fixed · daily loss 5% · min 4 trading days · 80% split · first payout after 14 days · $96 fee · fee refunded with payout #1.
Not simulated: Fees are EUR (€89-€1,080) at ~1.08 USD. Funded Standard account: no orders 2 min around major news, no holding over weekends (Swing account exempt).
Rules checked against the firm's site on 2026-10-28; firms change them often.
Net cash over time (payouts − fees)
Every account (13)
| # | Bought | Ended | Result | Trades | Time to pass | Payouts | Received | Fees |
|---|---|---|---|---|---|---|---|---|
| 13 | 2025-12-11 | – | Funded, still open | 122 | 5.8 months · 76 tr | 0 | $0 | −$96 |
| 12 | 2025-08-26 | 2025-12-11 | Blown in evaluation | 38 | – | 0 | $0 | −$96 |
| 11 | 2025-02-11 | 2025-08-26 | Blown when funded | 76 | 45 days · 19 tr | 1 | +$614 | −$96 |
| 10 | 2024-04-04 | 2025-02-11 | Blown when funded | 129 | 2.2 months · 28 tr | 3 | +$1,286 | −$96 |
| 9 | 2023-10-18 | 2024-04-04 | Blown in evaluation · passed phase 1 | 68 | – | 0 | $0 | −$96 |
| 8 | 2023-04-04 | 2023-10-18 | Blown in evaluation · passed phase 1 | 81 | – | 0 | $0 | −$96 |
| 7 | 2022-08-09 | 2023-04-04 | Blown in evaluation | 96 | – | 0 | $0 | −$96 |
| 6 | 2022-03-11 | 2022-08-09 | Blown when funded | 62 | 2.5 months · 32 tr | 0 | $0 | −$96 |
| 5 | 2021-03-26 | 2022-03-11 | Blown when funded | 128 | 6.9 months · 77 tr | 2 | +$167 | −$96 |
| 4 | 2020-10-30 | 2021-03-26 | Blown in evaluation | 55 | – | 0 | $0 | −$96 |
| 3 | 2019-10-01 | 2020-10-30 | Blown when funded | 153 | 2.6 months · 33 tr | 8 | +$3,706 | −$96 |
| 2 | 2019-03-29 | 2019-10-01 | Blown in evaluation | 73 | – | 0 | $0 | −$96 |
| 1 | 2019-01-02 | 2019-03-29 | Blown in evaluation | 36 | – | 0 | $0 | −$96 |
Replays this variation's backtest trades (raw costs: 1.00 spread) from 2019-01-02 to 2026-10-05, risking a fixed 0.5% of the account size per trade. A blown account is replaced at once; payouts are taken as soon as the rules allow. Floating losses use each trade's worst point on its own (open trades are not added together); the trading day runs 17:00 to 17:00 New York. Futures firms are simulated with the CFD backtest in R. Past results, not a forecast.